Renewable energy investment accelerates in the Middle East amid focus on energy security and infrastructure
New research finds EMEA Renewable Energy Infrastructure Investment Surges, Procurement Pressures Intensify Globally
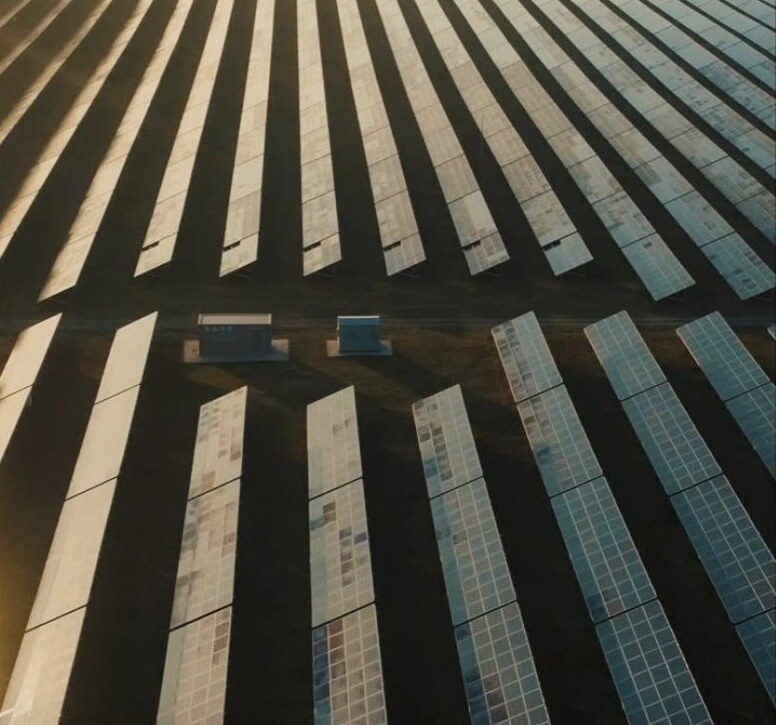
KSA – March 31, 2026: Investment in renewable energy projects in the Middle East has jumped by 28%, year-on-year, according to a new report from Ansarada, a leading procurement platform.
The 2026 Renewable Energy Infrastructure Outlook Report, produced in partnership with Infralogic, notes that globally, investment in the renewable energy sector has surged to a total of US$496B, with increasing AI compute demand cited as a key driver of this activity.
Investment in renewable energy projects in the Middle East totalled US$12.9 billion in 2025, up from US$10.1 billion in 2024.
Surveying 150 senior executives across APAC, EMEA, and the Americas, the report highlights how the Middle East is establishing itself as a strategic market, with 25% of respondents citing the region as a top growth market for renewable energy investment.
As Western markets grapple with grid congestion and permitting delays, the region's sovereign-backed model enables "rapid supply chain mobilisation and bankable pipelines," sidestepping the permitting friction and multi-year grid queue bottlenecks plaguing Europe and North America.
Saudi Arabia's US$8.4 billion NEOM Green Hydrogen Project exemplifies this approach, integrating 4 GW of generation directly with its electrolyser facility, building renewables and transmission in parallel. The project reached 80% construction completion in 2025, funded through a US$6.1 billion non-recourse package, the largest of its kind.
"What stands out is projects like NEOM, building renewables and transmission together,” said Justin Smith, Managing Director at Ansarada. "It's a different delivery model than what we typically see in Western markets."
The urgency is amplified by AI-driven energy requirements. With over US$500 billion in AI infrastructure capital expenditure projected for 2026 and US data centre energy consumption forecast to hit 409 TWh by 2030, the report identifies this as the primary catalyst for new renewable development, cited by 37% of respondents globally and 36% in EMEA.
"AI compute demand is the single biggest driver of new renewables development," Smith said. "But the shift from distributed solar to integrated, dispatchable systems, the 'solar-plus-storage' configurations needed to manage grid stability, dramatically increases procurement complexity."
The report reveals battery storage transitioning to essential infrastructure: 34% of EMEA respondents expect strong growth in large-scale storage. In EMEA broadly, macroeconomic uncertainties (44%) and high interest rates (44%) lead regional concerns.
Despite widespread technology adoption, the report exposes critical weaknesses. While 91% use purpose-built procurement software, organisations deploy an average of 3-4 disconnected systems, and 55% still rely on email for sensitive bidder correspondence.
"Organisations think they've digitised, but they've actually created a 'Frankenstack' of disconnected tools," Smith said. "The technology fragmentation gap was one of the most surprising findings."
Only 37% of respondents globally described their most recent procurement process as "very efficient," dropping to 8% in EMEA and 29% among government agencies. While 95% believe their processes are transparent internally, 43% admit processes lack clarity for external parties, creating litigation risk.
In EMEA, 80% of respondents deeply embed ESG in procurement, with 90% describing transparency and auditability as at least "very important." Without auditable ESG data, projects may not be eligible for tender or financing in many jurisdictions.
"The Middle East demonstrates what's possible when projects are designed holistically. That integrated approach, combined with proper digital infrastructure for procurement, separates projects that deliver from those that stall,” Smith concluded.
